Real estate · Real Estate
Blackstone’s opportunistic property values fall 3.2% in third quarter
Blackstone lowered valuations in older real estate funds as elevated interest rates delayed a recovery, while pointing to data center leasing and AI demand as sources of growth.
By Rian Keswicke · 4 min read
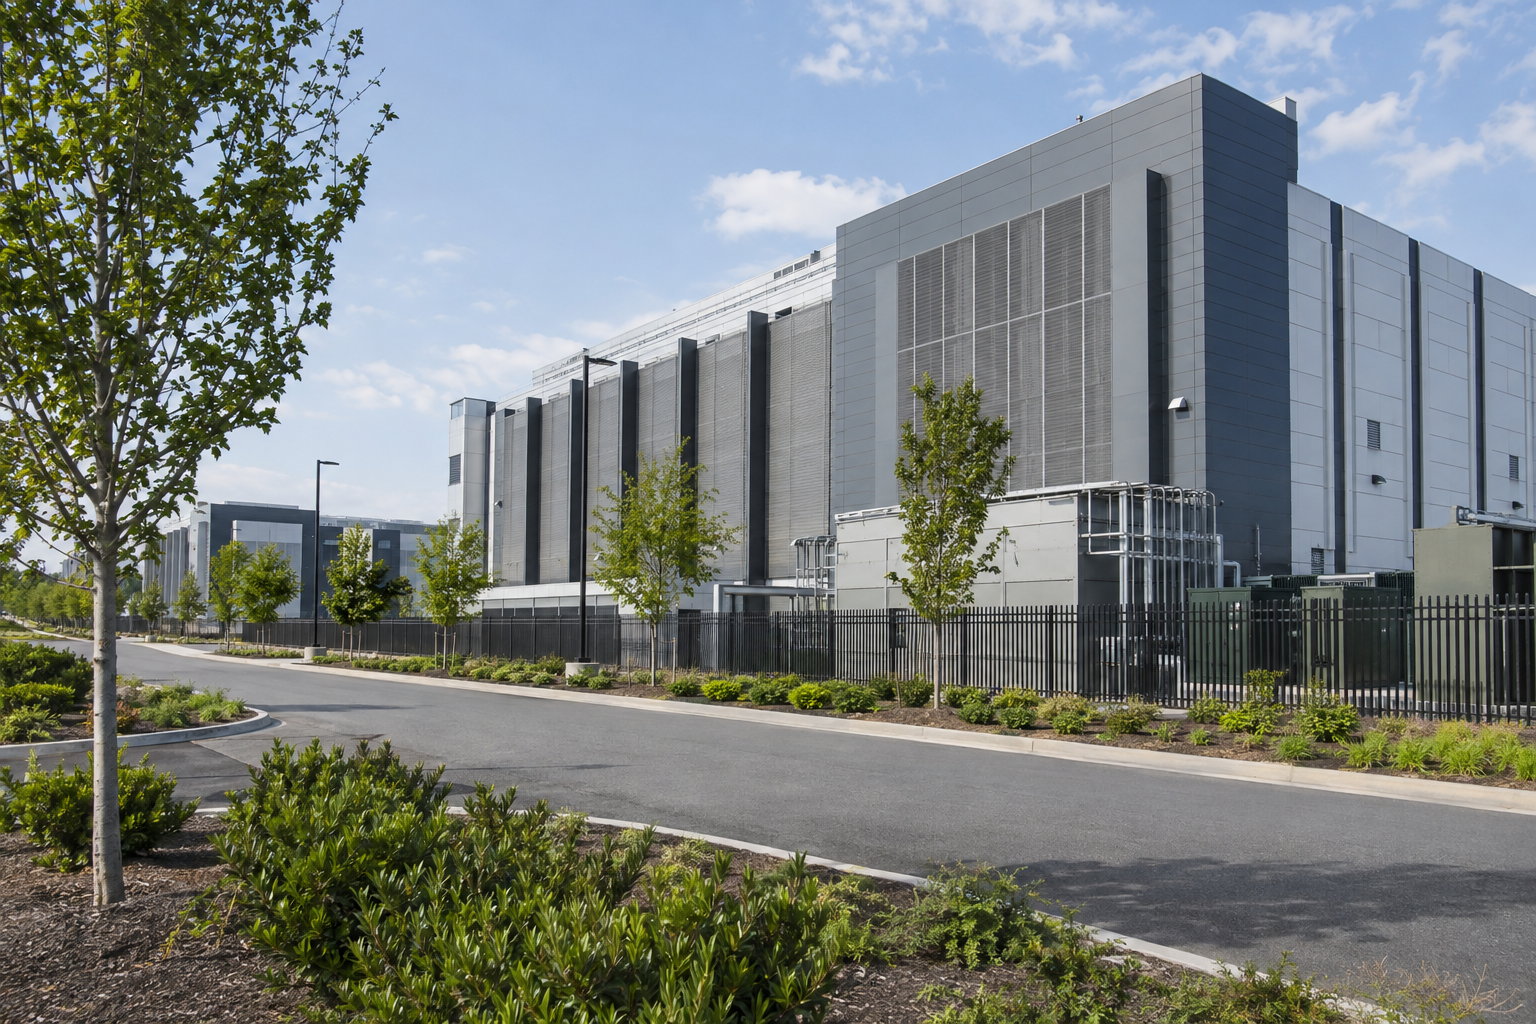
Blackstone marked down assets in its opportunistic real estate funds in the third quarter, as persistently elevated interest rates postponed the property-price recovery it has been expecting. The world’s largest real estate manager nevertheless maintained its positive outlook for data centers, arguing that demand for computing capacity and long-term customer contracts support the sector. The results show a divide within its property business: older opportunity funds faced valuation pressure, while newer funds and its core-plus business recorded gains.
Values in Blackstone’s opportunistic property vehicles declined 3.2% during the quarter and 4% over the past 12 months, the company said in its third-quarter results. Core-plus asset values, by contrast, increased 1.6% in the quarter and 4.3% over the year. Real estate assets under management stood at $309B, against $320B at the same point last year. Opportunistic real estate was the only part of Blackstone’s business to register falling values, making the weakness concentrated rather than uniform across the manager’s investment operations.
Blackstone told analysts that the reductions were in older funds, distinguishing those portfolios from more recent investments. Its latest global opportunity fund posted a 17% increase in values over the past 12 months, while its latest European fund recorded a 13% gain. Those figures complicate any reading of the overall opportunistic decline as a single measure of property-market performance. They also show that the company’s newer funds have delivered positive results even as higher interest rates continued to weigh on older holdings.
Read more: Zillow economist sees roughly 25-30 percent chance of mortgage rates reaching 8 percent
President Jon Gray argued that the operating backdrop for real estate was more supportive than in 2022, when Federal Reserve rate increases coincided with slowing cash-flow growth and substantial construction pipelines. In his account, record-low new construction and readily available debt now provide support, even though higher rates remain an obstacle to recovery. The distinction is central to Blackstone’s outlook: the company is acknowledging pressure on valuations while arguing that conditions affecting the underlying properties are improving rather than deteriorating across the board.
Data centers are a prominent part of that case. Gray said leasing in Blackstone’s data center portfolio would triple this year to about 6 gigawatts. He also highlighted demand in logistics, where U.S. leasing was up 45% this year. Together, data centers and logistics represent 54% of Blackstone’s real estate portfolios. The company expects strength in those sectors to offset weaker areas, including multifamily. That concentration gives leasing activity in computing infrastructure and warehouses particular importance to the performance of its broader property holdings.
Gray’s confidence in data centers also rested on the nature of their customers and contracts. Roughly 96% of Blackstone’s data center leases are supported by long-term agreements with blue-chip companies, he said. He argued that computing demand is expanding faster than supply and that businesses’ adoption of artificial intelligence should sustain that imbalance as they pursue productivity gains. Gray described AI infrastructure as the area generating Blackstone’s highest returns, presenting it as a source of investment performance despite the valuation weakness elsewhere in real estate.
Read more: Russian strikes kill 7 in Ukraine amid push to resume peace talks
The division’s earnings nevertheless fell 10%, showing that stronger performance in selected portfolios did not prevent a broader decline in income. Fees tied to exceeding performance benchmarks rose 29%, but fees from asset sales and profits from investing Blackstone’s own money alongside clients each dropped 25%. Management fees also declined as the asset base contracted. The combination separates portfolio performance from the division’s earnings picture: gains in some funds coexisted with lower income from selling assets, co-investments and managing a smaller pool of capital.
Blackstone’s optimism sits alongside more cautious signals elsewhere in commercial property. Prologis has warned that higher borrowing costs will slow industrial transactions and development, while Newmark has identified $179B in low-rate real estate loans exposed to refinancing risk. Those concerns highlight financing constraints rather than contradicting Blackstone’s reports of stronger leasing. They frame the tension in Gray’s assessment: improving demand for particular property types can provide support without removing the pressure that borrowing costs place on investment activity and asset values.
Blackstone continued both selling and buying property during the quarter. It disposed of $7B of assets, including offices in India and logistics properties in Japan, compared with $7.3B in the third quarter of 2025. Investment reached $6.3B, against $3.6B a year earlier. The company also highlighted its purchase of the Hyatt Regency Embarcadero in San Francisco for $280M in June. The transaction figures show continued deployment of capital even as the company reduced valuations in its older opportunistic portfolios.
For further investment, Blackstone said it had $47B available for real estate. It raised $6.3B for property funds during the quarter, compared with $3.8B in the third quarter last year. Core-plus and debt strategies accounted for most of the fundraising, attracting $3.3B and $2.3B, respectively. That capital provides scope for additional deployment while the recovery remains delayed. Blackstone’s outlook continues to depend on its contention that stronger property fundamentals, particularly in data centers and logistics, can counter the drag from elevated interest rates.