Oil markets · Markets
Brent crude tops $113 as supply threats push prices to highest since May
Oil prices reached a five-month high as attacks threatened global supply and Trump indicated possible action on Iran, while European shares fell amid expectations of higher inflation and borrowing costs.
By Sera Wyclen · 3 min read
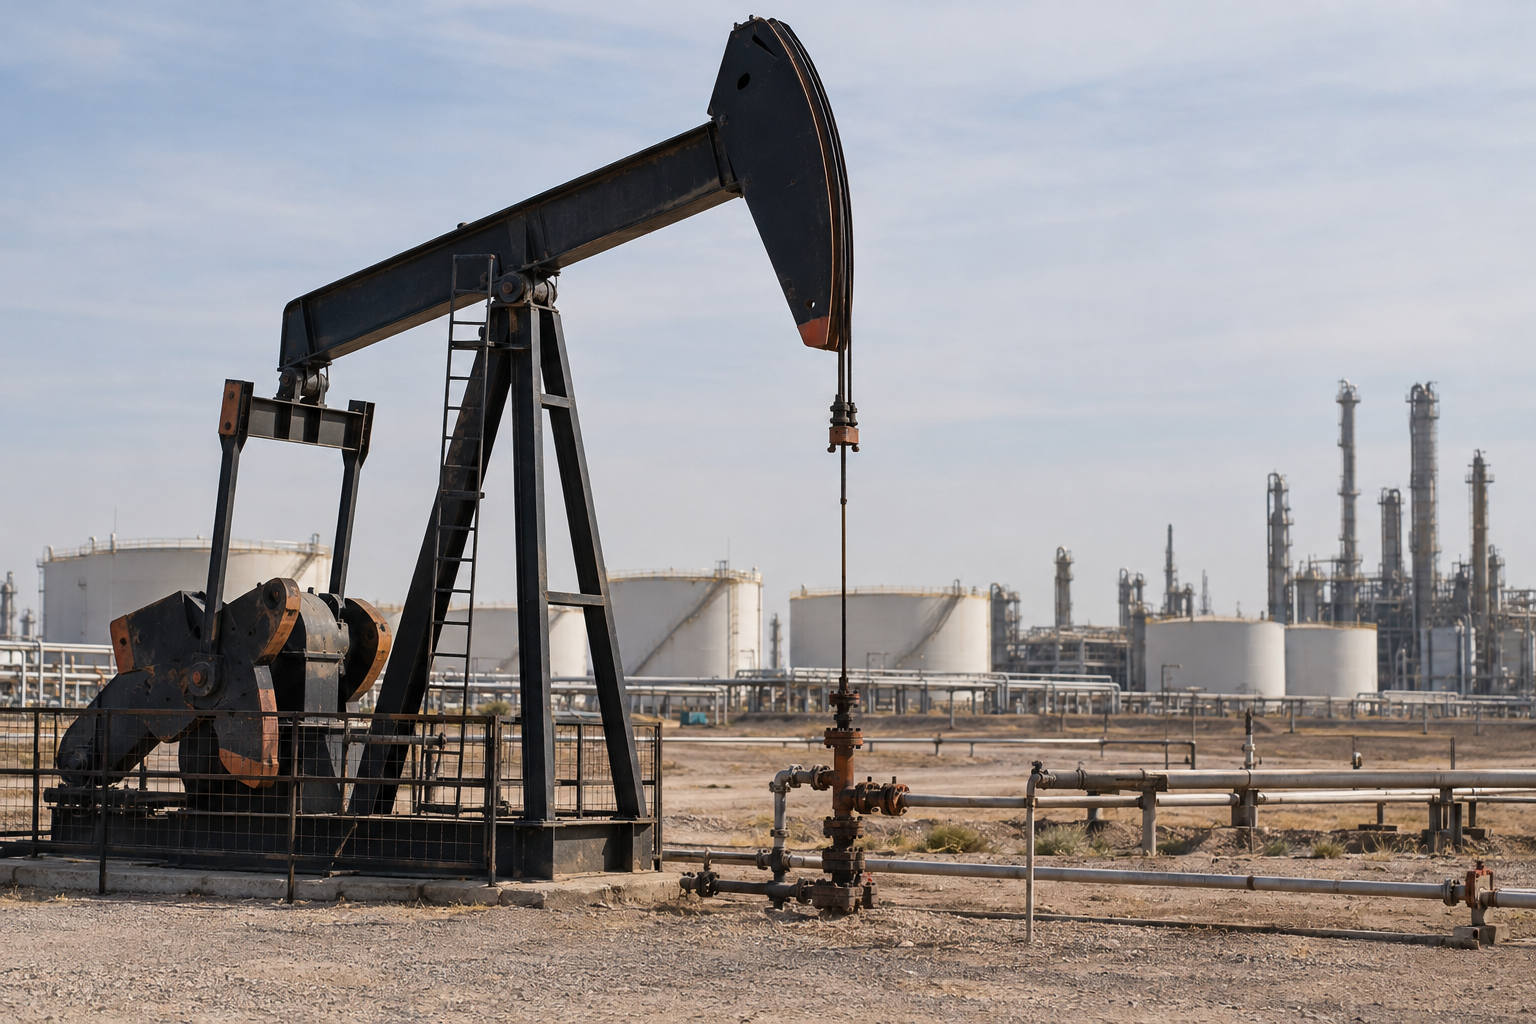
Brent crude rose above $113 to its highest level since May as attacks threatened global oil supply and Trump hinted at possible action on Iran. The increase came as global stocks wobbled on Thursday amid expectations of higher inflation and borrowing costs. The reports brought supply concerns and the prospect of action involving Iran into focus alongside worries about the outlook for shares.
The Stoxx Europe 600, which tracks the continent’s biggest companies, fell by 1%, while the UK’s FTSE 100 declined by 0.7%. Oil’s rise marked a five-month high, with Brent crossing the $113 threshold. A separate market update reported a 2% decline in the Nasdaq amid concerns about artificial-intelligence spending and the increase in oil prices. These reports showed pressure on European shares and the Nasdaq, although the supplied information does not establish that all the declines occurred in the same trading session.
The reported oil-market backdrop was a threat to global supply from attacks, rather than a quantified account of how much production had been lost. That distinction matters in assessing the price movement: Brent’s rise was clear, but the available information did not establish the scale or duration of any interruption. The reported market development was therefore a higher crude price against a backdrop of supply uncertainty, without figures showing the volume of oil affected by the attacks.
Read more: Nasdaq falls 2.1% as AI-spending concerns and higher oil weigh on stocks
Trump’s indication of possible action on Iran accompanied that uncertainty. The signal concerned potential action, not a confirmed operation, and the supplied information contained no details establishing its scope or timing. For the oil market, the distinction between a hint and an implemented measure remains important. Brent’s move above $113 followed the indication, but the information available does not isolate how much of the increase reflected that signal rather than the wider concern over attacks threatening supply.
The comparison with May places the latest price in a longer perspective than a single trading session. Brent had reached a level not seen since then, while oil prices were also described as reaching a five-month high. That is a measure of where the price stood relative to its recent history, rather than a measure of the day’s gain. No exact percentage increase for Brent was provided, so the $113 threshold and the comparison with May are the clearest available benchmarks for oil.
In Europe, the equity figures offered a more precise account of the reported declines. The 1% fall in the Stoxx Europe 600 was larger than the FTSE 100’s 0.7% retreat, with both moving lower amid expectations of higher inflation and borrowing costs. Those figures establish the direction of the moves, but do not identify which companies or industries contributed most. They also do not provide a basis for assigning the declines entirely to the rise in crude.
Read more: 10-year Treasury yield falls below 5% to lowest in nearly a month
The separately reported Nasdaq fall of 2% highlighted another concern for equity investors: spending on artificial intelligence. Higher oil prices were part of the backdrop, but they were not the only issue associated with that decline. This makes a single explanation for the reported weakness in shares incomplete. The European market account emphasised inflation and borrowing costs, while the Nasdaq update also cited unease over AI spending, leaving different pressures in view across the reported share-market declines.
The contrast between rising crude and Thursday’s unsettled global stocks was a cross-market development. Oil prices were rising as supply came under threat, while equities faced expectations of higher inflation and borrowing costs. Even so, those expectations should not be confused with a reported change in inflation itself or a confirmed increase in borrowing rates. The available figures describe market prices and the concerns surrounding them; they do not establish how those concerns will translate into subsequent economic data.
Questions left open by the reports include whether the attacks disrupted supply and whether Trump’s suggestion of action on Iran becomes more definite. Neither the amount of supply at risk nor the details of possible action were specified in the supplied information. Without that information, these reports provide no basis for estimating a supply shortfall or projecting a further oil-price increase. An unresolved question is how the threats accompanying the rally develop, rather than whether Brent has already reached a recent high.
For now, the established picture is of Brent above $113 at its highest since May, alongside Thursday’s declines in major European share indices. Further clarity on the attacks and on possible action involving Iran would help distinguish immediate supply concerns from uncertainty about what might follow. In equities, the reports point to inflation and borrowing-cost expectations accompanying Thursday’s weakness, while AI-spending concerns complicate any reading of the separately reported Nasdaq decline as solely a response to oil.