Real estate · Real Estate
REITs find a supply cushion as interest rates rise
Higher borrowing costs can strain commercial property, but their dampening effect on development is helping the sector withstand renewed rate pressure.
By Rian Keswicke · 3 min read
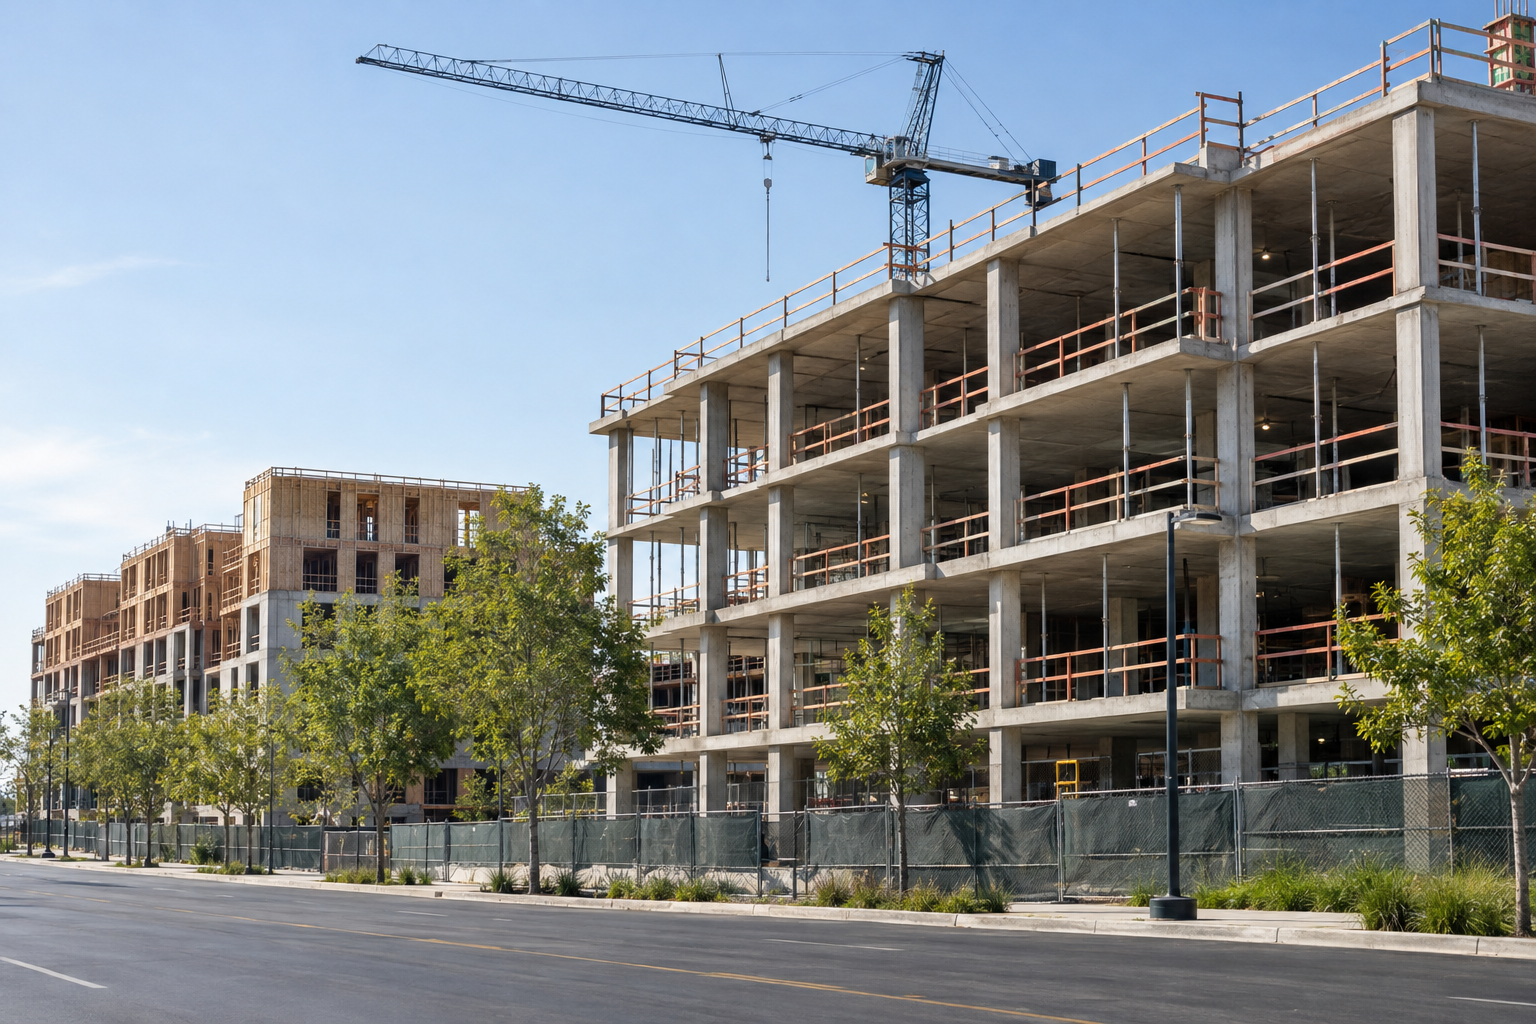
Real estate investment trusts are finding some protection from rising interest rates in a consequence of the earlier commercial-property downturn: the difficulty of getting new developments off the ground. More expensive borrowing weighed on property values from 2022 through 2024, but its effect on development is now helping the sector.
The contrast is between two forces, rather than a disappearance of the sector’s sensitivity to borrowing costs. From 2022 through 2024, higher rates reduced asset values by making borrowing more expensive. Several property sectors also faced substantial new supply, which slowed growth in rents and cash flow. In the current rising-rate environment, the difficulty of undertaking new development provides a counterweight. The same financing pressure that can hurt existing asset values also makes the creation of competing space more difficult.
The earlier downturn was therefore not simply a story about interest rates. The supply of property mattered alongside the cost of financing it. Higher borrowing costs weakened values, while new space put pressure on the growth of income from buildings. Those effects operated through different parts of the property market, but both were adverse for the sector. Looking only at rates would miss the additional strain that new supply placed on rents and cash flow during that period.
Read more: Trump’s reported reluctance raises questions over future US support for Ukraine
That distinction helps explain why a renewed rise in rates need not produce an identical outcome for REITs. Higher rates still make financing more expensive, but development provides an offset: expensive borrowing has made new projects harder to pursue. To the extent that this limits additional supply, it reduces one of the pressures that accompanied the earlier downturn. The explanation for the sector’s greater resilience rests on that offset, not on evidence that interest rates have ceased to matter for property.
Asset values remain a reason for caution. A more difficult development environment does not remove that relationship, nor does it establish that existing assets are insulated from further rate increases. The supportive supply effect and the negative financing effect can coexist. The question for the sector is how far the former can soften the latter, rather than whether one has entirely displaced the other.
Rents and cash flow provide the other part of the comparison. During the downturn, new supply in several sectors slowed their growth, adding an operating pressure to the financial one. Making development more difficult offers a potential restraint on that source of competition. It is a reason to distinguish the outlook for income from the outlook for asset values: borrowing costs may still weigh on valuations even as constraints on development potentially ease competitive pressure on property income.
Read more: Zillow reports sharp fall in pending home sales as rents hold firm
The benefit also needs to be described narrowly. Slower growth in rents and cash flow is not the same as a decline in either, and the earlier supply pressure affected several sectors rather than being established as uniform across commercial property. Equally, the current help from constrained development should not be read as proof of stronger conditions everywhere. The available comparison supports a more resilient sector, but not a conclusion that every REIT or property category faces the same balance of pressures.
A cautious reading emphasises the cost of borrowing; a more constructive one focuses on the difficulty of adding supply when those costs are high. Both interpretations follow from the same experience. What looks beneficial now is thus connected to what was painful earlier. For REITs, the distinction is important: resilience can come from a less adverse competitive backdrop even when the immediate financing environment remains challenging.
This makes the current position more nuanced than a straightforward recovery from higher rates. The sector is receiving help from a constraint on development, rather than from cheaper borrowing. That is a qualified source of support, because the condition limiting development can also weigh on property values. It nevertheless changes the comparison with the earlier downturn, when substantial new supply added to the damage from rising financing costs instead of offering the prospect of relief from competition.
What comes next will depend in part on the interaction of those forces. Continued difficulty in pursuing development could sustain the mechanism now helping the sector, while further borrowing-cost pressure could renew the valuation challenge. Rents and cash-flow growth are relevant to judging that balance because they were where additional supply previously made itself felt. REITs have a supply-side cushion in this rate environment, but the case for resilience remains one of partial protection, not immunity from higher interest rates.