Vietnam · Opinion
Vietnam’s growth ambitions confront a capital constraint
Vietnam’s ambition to become a high-income country by 2045 raises a difficult question: whether to adjust growth targets to available capital or accept considerably greater economic risk.
By Editorial Board · 4 min read
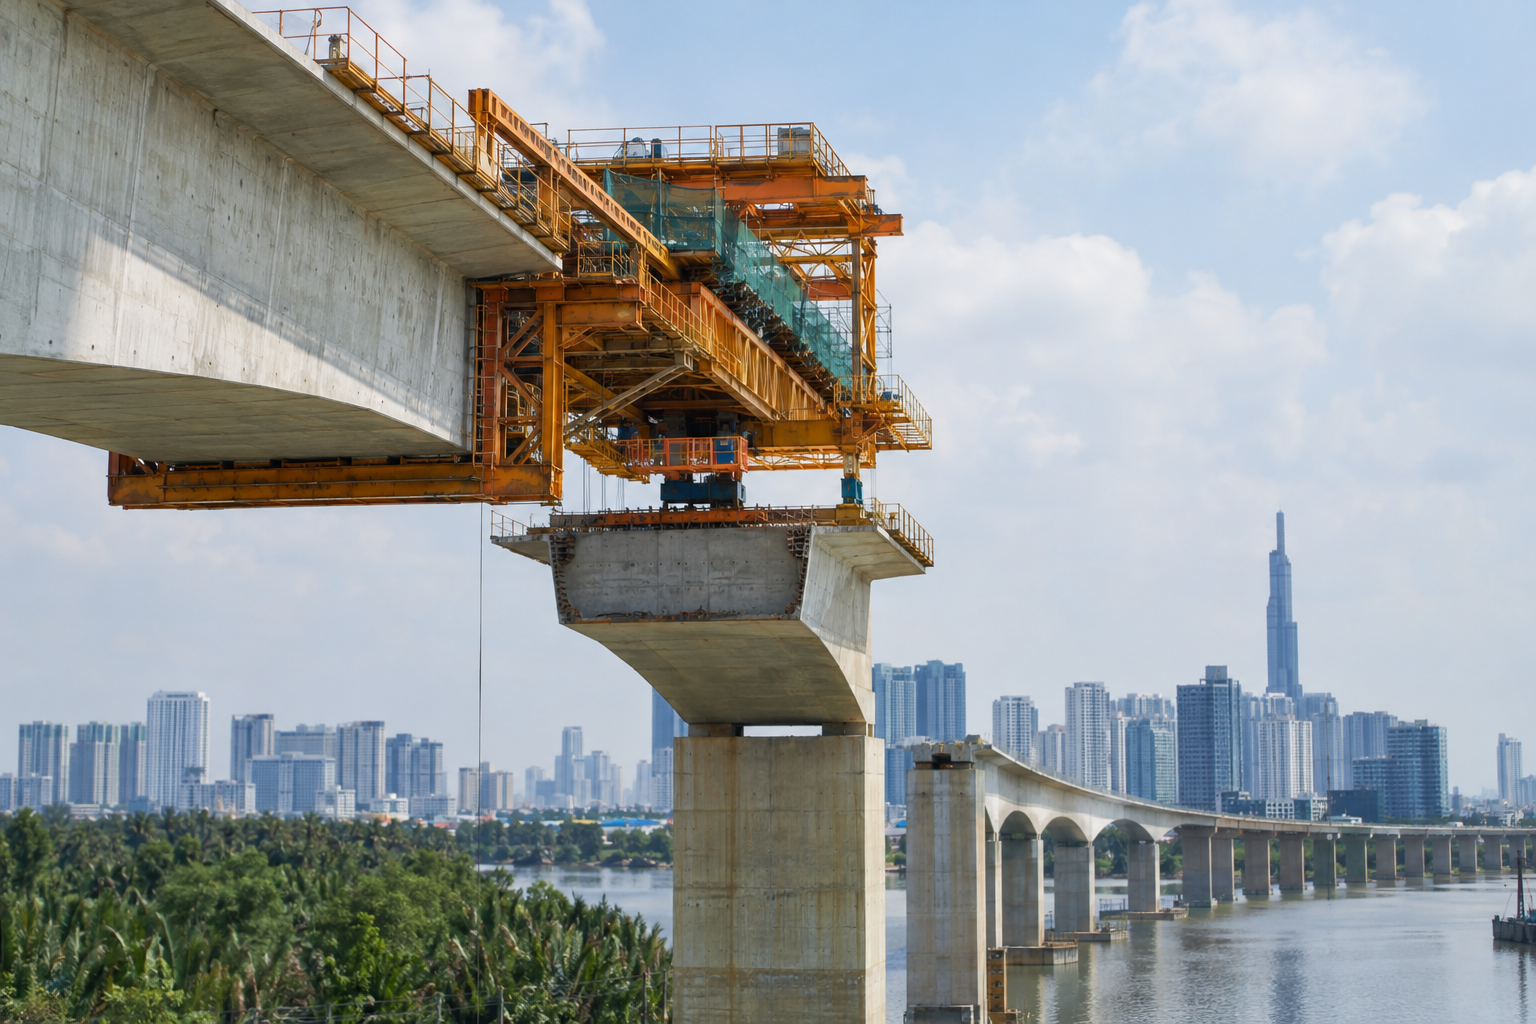
Vietnam’s development ambition poses a question that a destination alone cannot answer: how much risk should the country accept to reach it? The tension is between the income status its leadership wants and the capital available to support that aspiration. An ambitious target can establish a direction without settling the practical choices along the way. Equally, acknowledging a financing constraint does not, by itself, establish that the ambition should be abandoned. The difficult judgement lies between those positions.
Since taking power in August 2024, General Secretary To Lam has stressed the objective of making Vietnam a high-income country by 2045. In an opinion piece, Le Hong Hiep frames the financing dilemma as a choice between bringing growth targets into line with the capital Vietnam can obtain and accepting substantially greater economic risks. These are distinct propositions: To Lam supplies the long-term ambition, while Hiep questions the conditions under which it can be pursued. Neither proposition, on the information provided, establishes a detailed financing strategy.
The distinction matters because the supplied excerpt gives a deadline but no quantified measure of the capital constraint. It gives no investment requirement, financing shortfall or annual growth target against which to test the ambition. The dates establish the political starting point and intended destination; they do not demonstrate whether the resources are sufficient. A numerical verdict on feasibility would therefore go beyond the evidence supplied. The analysis must instead examine the choice Hiep identifies, while keeping the limits of that evidence visible.
Read more: America’s 100% tariff does not settle the Chinese EV question
The strongest argument for the adjustment option Hiep sets out is consistency between objectives and resources. If the capital Vietnam can raise is insufficient for its intended growth path, revising that path would acknowledge the constraint rather than assume it away. This argument need not amount to rejecting higher incomes as a national objective. It distinguishes the desired outcome from the pace at which it can be reached. Its limitation here is that the supplied excerpt does not establish how large an adjustment would be necessary.
To Lam’s stated ambition places the desired destination at the centre of the discussion. The strongest case for retaining that ambition is that a long-term objective and a fully financed programme are not the same thing: uncertainty about the latter does not logically disprove the former. But this is a defence of keeping the objective, not evidence that any particular route is viable. Nothing supplied establishes that To Lam has endorsed greater economic risk as the means of achieving high-income status.
The alternative in Hiep’s formulation is to accept considerably greater risk rather than align growth targets with obtainable capital. Its attraction would depend on whether maintaining the intended trajectory justified that additional exposure. Yet the supplied excerpt does not identify the risks, quantify them or describe who would bear them. It would be unwarranted to fill those gaps with claims about particular financing instruments or economic vulnerabilities. The relevant comparison remains conditional: a more ambitious path would require a stronger justification if it involved greater risk.
Read more: U.S. reduces embassy staffing as warnings of Iranian threats intensify
This is also why the argument should not be presented as a documented confrontation between rival policy camps. The supplied positions are a leader’s development objective and an opinion writer’s warning about the choices behind it. There is no basis here to assign either a financing plan or a willingness to sacrifice economic stability to the leadership. Nor does Hiep’s warning establish that lower growth targets are the only defensible response. His formulation identifies a trade-off; the supplied excerpt does not provide the figures needed to resolve it.
The central analytical task is to separate ambition, feasibility and acceptable risk. Ambition concerns the outcome Vietnam seeks. Financial feasibility concerns whether the necessary capital can be obtained. Acceptable risk concerns the terms on which the country would pursue the objective if financing remained constrained. Treating these as interchangeable would obscure the decision. A target does not prove feasibility, while a constraint does not settle what risks are worth taking. Each question requires an answer before the overall strategy can be assessed with confidence.
What comes next, analytically, is a need for evidence rather than a presumed policy outcome. A firmer assessment would require a stated capital requirement, an account of financing that could realistically be secured and an explanation of the risks attached to the proposed route. Those are requirements for evaluating the ambition, not claims that such details have been announced. Without them, neither confidence in the target nor scepticism about it can become a well-supported judgement about Vietnam’s likely economic trajectory.
Vietnam’s choice is therefore more demanding than a simple contest between optimism and restraint. To Lam’s objective establishes the scale of the aspiration; Hiep’s warning asks whether the means and risks can be reconciled with it. The strongest balanced conclusion is not that growth targets must be reduced, or that greater risk must be accepted. It is that the deadline cannot substitute for a financing case. How convincingly that case is made will determine how the competing arguments should be weighed.